Residential building lots
Buying a site for a future home? Clarify the current zoning, legal access, available services and intended building timeline. Ask what the acquisition loan covers before planning the build.
TORONTO · MISSISSAUGA · THE GTA
The right land starts with a clear plan.
Explore land purchase financing in Mississauga, Toronto and across the GTA, from a future home site to a commercial development property.
Share the property, purchase price and what you plan to do next.
Toronto officeServing borrowers across the GTA
Established in 1997Mortgage brokerage experience
Brokerage licence 10533Residential & commercial financing
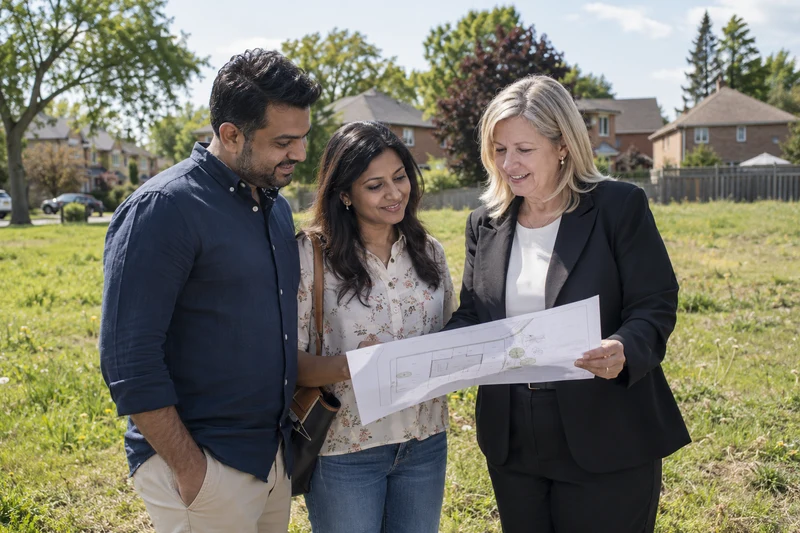
LAND PURCHASE FINANCING IN THE GTA
A land acquisition mortgage helps finance the purchase of a parcel of land. The review considers the property in its current condition, your financial position and how you intend to repay the loan. Buying the site and funding construction are separate questions.
The Mortgage Providers helps buyers explore land purchase financing in Mississauga, Toronto and across the GTA. Whether you have found a residential lot or a site for a future commercial project, start with the address, asking price and intended use.
A promising location is only part of the decision. Access, servicing, zoning and the time needed to move your plans forward can all affect whether the purchase works.
WHAT ARE YOU BUYING?
Describe the land as it stands today, along with what you hope to do with it.
Buying a site for a future home? Clarify the current zoning, legal access, available services and intended building timeline. Ask what the acquisition loan covers before planning the build.
A property with an existing building may involve demolition or a change in use. Explain what is on the site now, which approvals are in place and which are still being pursued.
For a business site or land held for future development, explain the intended use and holding period. Confirm what servicing, studies and approvals may still be needed.
FROM ENQUIRY TO FINANCING REVIEW
Involve your mortgage broker early, while there is time to review the property and obtain the information a lender needs.
Provide the address or legal description, purchase agreement if available, deposit, closing date and intended use.
Separate confirmed facts from assumptions about zoning, services and development potential. Ask your lawyer and planning professionals what needs further review.
Explain your available cash, other debts and how you will cover payments and property expenses while holding the land.
Review the loan amount, net funds at closing, interest, fees, term, conditions and payout costs. Explain how the mortgage will be repaid if the project takes longer than expected.
BEFORE YOUR CONVERSATION
Available documents help make the first review more useful. Depending on the site and lender, these may include:
Ask which reports the lender requires and who may prepare them before paying for new work.
BUDGET BEYOND THE PURCHASE PRICE
Allow for interest, property taxes, legal work, lender and brokerage fees, appraisal costs and any required site studies. Ask your lawyer or tax advisor which transaction taxes apply. Include servicing and approval expenses where relevant to your project.
For example, if you intend to move into construction financing after receiving approvals, ask what happens if those approvals arrive after the land mortgage matures. An extension, refinance or sale should not be treated as automatic.
Compare the cash you receive at closing with the cash you need. Fees deducted from an advance can leave less money available than the headline loan amount suggests.
MISSISSAUGA · TORONTO · GTA
A vacant Mississauga lot, a Toronto redevelopment property and undeveloped land elsewhere in the GTA can raise very different questions. Avoid assuming that a nearby project proves the same use is possible on your site.
Confirm the relevant planning authority, access and servicing arrangements. Where applicable, ask qualified professionals about environmental conditions, floodplain restrictions or other constraints before committing to your plan.
Considering a business property? Visit our commercial mortgages page. If private funding is proposed, review our private mortgage guidance for questions about costs and repayment.
YOUR QUESTIONS
Answers about equity, property review and the next financing stage.
Financing may be available, depending on the land and your application. A lender may review location, access, services, zoning, value, your available equity and the repayment plan. The Mortgage Providers can discuss the property and explore options; not every site will qualify.
There is no single down payment that applies to every land purchase. The required contribution depends on the lender, property assessment and proposed terms. Ask for the amount you must contribute at closing, including costs that the loan will not cover.
Raw land generally has little or no servicing or development in place. A serviced lot has some infrastructure available, but the term does not confirm that every connection is installed, paid for or sufficient for your project. Verify access, service capacity and connection costs for the specific property.
Not automatically. Acquisition financing funds the land purchase under its agreed terms. Construction funding involves a further review of the project, budget, approvals and funding schedule. Ask whether the proposed arrangement covers both stages or whether a separate construction loan will be needed.
It may be possible, but pending approvals create uncertainty for both the purchase and financing. Tell the lender what is approved and what is only proposed. Obtain planning and legal advice, and do not assume the land will be valued or financed as though a future use is already permitted.
A refinance may be possible if a lender accepts the property and there is sufficient equity for the proposed borrowing. Provide the current mortgage balance, property details and purpose of the funds. Future development value is not automatically accepted as current lending value.
Compare interest, lender and brokerage fees, legal and appraisal costs, required reports, payment structure and any renewal or early payout charges. Confirm the net advance, your total cash contribution and how long the mortgage lasts. Include property carrying costs in your own budget.
The land mortgage remains subject to its repayment terms even if your plans are delayed. Discuss a contingency before closing, including the cash needed to keep carrying the property. A lender extension, new construction loan, refinance or sale is not guaranteed.
LET’S DISCUSS YOUR NEXT STEP
Share the location, purchase price and your plans.
We’ll discuss what the land financing review needs.
Sign up for our weekly or monthly newsletters packed full of the latest mortgage related news.